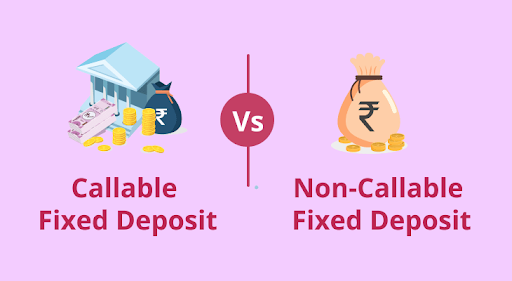
In the financial world, Fixed Deposits (FDs) are widely regarded as stable investment instruments. They offer guarantee returns and are considered relatively low-risk compared to other investment vehicles. However, understanding the nuances of different types of FDs can be crucial for optimizing your investment choices. Among these, the distinction between callable and non-callable FDs stands out. In this article, we will explore the user journey in understanding callable vs non callable FDs, examining the pros and cons of each type to help you make an informed financial decision.
What Are Fixed Deposits?
Before diving into the comparison of callable and non-callable FDs, let’s briefly understand what Fixed Deposits are. An FD is a financial instrument offered by banks and financial institutions that allows you to deposit a sum of money for a fixed period at a predetermined interest rate. The principal amount remains unaffected, while the interest accrued is either paid out periodically or at maturity.
Callable Fixed Deposits
Definition
Callable Fixed Deposits allow the bank or financial institution to “call” the deposit before its maturity date. Essentially, they retain the right to terminate the investment early, thereby returning the principal and any earned interest back to the investor.
Pros of Callable FDs
- Higher Interest Rates: Callable FDs generally offer higher interest rates compared to non-callable alternatives. This can be attractive for investors looking for better returns.
- Flexibility for the Bank: As interest rates fluctuate, banks can manage their liquidity better with callable FDs. This means they might offer more attractive rates during periods of low inflation.
- Possibility of Reinvestment: If the FD is called, investors have the opportunity to reinvest their savings at potentially higher interest rates if market conditions improve.
Cons of Callable FDs
- Early Termination: The risk that your investment may be called unexpectedly can pose a significant drawback. If interest rates increase or market conditions favor the bank, they may terminate your FD prematurely.
- Opportunity Cost: You might miss out on long-term gains. If the market is volatile and your callable FD is called early, you may not have the opportunity to benefit from prolonged stability.
- Lower Predictability: With callable FDs, future investment income may be more uncertain, as you do not know when or how often the bank will call your deposit.
Non-Callable Fixed Deposits
Definition
Non-callable Fixed Deposits, as the name implies, cannot be terminated before the maturity date by the bank. Once you choose this type of FD, your investment is secure until the agreed maturity period is reached.
Pros of Non-Callable FDs
- Predictable Returns: Investors benefit from knowing exactly how much interest they’ll earn over the investment period, providing a sense of financial security.
- Fixed Tenure: Non-callable FDs assure you that your investment will remain intact for the agreed duration, which can be beneficial for long-term financial planning.
- Lower Risk: Since there’s no possibility for the bank to terminate the deposit prematurely, you can avoid the uncertainty associated with the callable option.
Cons of Non-Callable FDs
- Lower Interest Rates: Generally, non-callable FDs offer lower interest rates than callable FDs due to the absence of the flexibility for banks. This may chase away some investors looking for more aggressive returns.
- Opportunity Cost for Investors: If the market interest rates increase after you’ve invested, you might find your money stuck in a lower-yielding FD while missing out on better financial opportunities.
- Cash Flow Constraints: Non-callable FDs require you to lock away your investment for the entire tenure, which could be a limiting factor if you need immediate liquidity in emergencies.
Making Your Choice: Factors to Consider
When weighing callable vs non callable FD, several factors come into play:
- Interest Rate Environment: In a rising interest rate environment, you might prefer non-callable FDs to lock in current rates rather than risk being called early.
- Financial Goals: Consider your long-term financial goals. If you’re looking for ultra-stable investments, non-callable FDs may work better. In contrast, those aiming for potentially higher returns may lean towards callable options.
- Risk Tolerance: Assess your risk appetite. If you prefer predictable returns with lower risk, non-callable FDs are more suitable. If you’re comfortable with some uncertainty for possibly better gains, callable FDs could be your go-to choice.
- Investment Tenure: Longer investment horizons may be well-suited for non-callable FDs, whereas callable FDs could be more appealing for shorter investment durations.
Conclusion
Understanding callable vs non callable FDs can play a crucial role in achieving financial stability and maximizing returns on your investments. Each option comes with its own set of advantages and disadvantages, which should align with your individual financial goals and risk tolerance. By weighing the pros and cons of FD options, you can determine the one that best suits your financial strategy. Remember to assess market conditions, your investment objectives, and your comfort with uncertainty before making the final decision. Making an informed choice today can lead to sustainable financial health tomorrow.
When it comes to investing, the more informed you are, the more empowered you’ll be in your financial journey.

+ There are no comments
Add yours