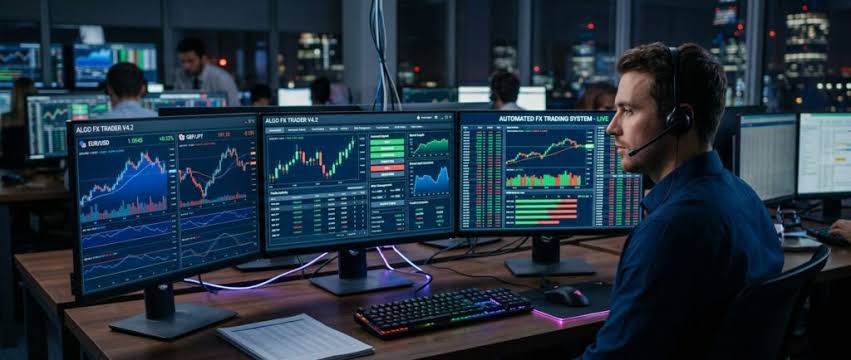
Performance summaries that only show the highlight reel rarely capture what actually determines whether a trading strategy survives contact with real market conditions over time. A single strong quarter posted proudly on social media tells almost nothing about how that same account behaved during the stretch immediately before or after, which is exactly the gap that detailed statistics tracking exists to close for anyone willing to look past the flattering headline number.
Drawdown depth separates strategies that merely look good from those that actually hold up under stress, and this is where raw return figures alone fall dangerously short. Tracking maximum drawdown alongside average drawdown is where myfxbook adds real value, giving a far more textured picture of how much pain an account absorbed measured against the gains eventually posted, since two strategies with identical annual returns can carry wildly different risk profiles depending on how deep and how long each drawdown period actually ran.
Consistency across different market regimes carries weight many traders initially fail to appreciate when evaluating a system’s verified history. A strategy that performed brilliantly during a trending currency environment might struggle considerably once markets shift into a tighter, range-bound pattern, and statistics spanning multiple distinct periods reveal that fragility in a way a single cherry-picked quarter never could. Traders who only examine a strategy’s best three months end up with a badly skewed sense of what to expect going forward. Trade duration and frequency data add texture that raw profit figures alone cannot provide. A strategy generating steady returns through dozens of small trades each week behaves completely differently from one relying on a handful of large, infrequent positions, even if both produce similar percentage gains over the same stretch of time. Understanding which pattern actually generated the numbers matters considerably for anyone trying to judge whether a strategy fits their own risk tolerance and available screen time.
Verified account linking through myfxbook distinguishes genuine track records from numbers typed manually into a spreadsheet, and that distinction carries real weight in a space where fabricated performance claims circulate constantly. Automatically synced statistics pulled directly from a live or demo account remove the possibility of selective reporting, since every trade gets logged automatically, not curated after the fact by whoever wants to look impressive to potential followers.
Correlation analysis between different tracked strategies offers a less obvious benefit that experienced traders tend to value considerably, often overlooked by newcomers early on. Running two systems that look independently profitable can still produce a combined portfolio with risk neither system reveals on its own, if both strategies happen to perform well and poorly during overlapping conditions, a pattern that only becomes visible once traders compare statistics side by side, not evaluating each system in isolation.
Best and worst period comparisons ultimately matter because markets never stay in one regime indefinitely, and a strategy untested against genuinely adverse conditions carries hidden risk that a shiny recent track record can easily disguise. Reviewing the full span of available statistics, well beyond whichever window happens to flatter the numbers most, gives traders a considerably more honest basis for deciding whether a given approach deserves real capital or just continued observation from the sidelines.

+ There are no comments
Add yours